Tax Documents and Other Notices are Available Online!

Tax Documents and Other Notices are Available Online!

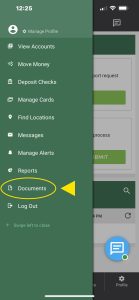
Digital Banking App Screenshot

App screenshot

Just in time for tax season, we have expanded our electronic documents to include tax docs, loan statements, and NSF notices. It’s easy to set up. Go to the Documents tab on the left side and follow the prompts.

Or, use the Digital Banking Guide for step-by-step instructions to set up your electronic documents so you can access items when needed!
My Digital Documents

When you first click on the Documents tab, you’ll be prompted to accept updated terms and conditions. This includes permissions for all electronic notices and statements, whereas the previous version only included electronic account statements.

Download the app for banking when and where you need it!

Digital Banking Guide Cover Android App on Google Play

A Guide to the Corporate Transparency Act for Missouri Business Owners

As a Missouri business owner, navigating the complexities of business regulations is challenging. Now, there’s a new law in effect that every owner needs to know about: the Corporate Transparency Act (CTA). While the thought of tackling another requirement may feel daunting, rest assured that The Callaway Bank’s Business Banking Team is here to guide you through the process.  

Helpful CTA Links for Missouri Business Owners

What Is the Corporate Transparency Act?  

Effective January 1, 2024, the CTA is designed to increase corporate accountability. The law introduces a critical requirement that many businesses must comply with — the Beneficial Owner Information Report (BOIR). The goal is to boost transparency in business operations to prevent fraud and illegal activities like money laundering. 

Review CTA Reporting Requirements  

A brunette Missouri Business Owner on the phone at his desk, smiling What Is the Beneficial Owner Information Report?  

As the key component of CTA, BOIR involves providing important details about the company’s beneficial owners. While the specifics vary based on the type of ownership, it typically includes names, addresses, and other identifying and trackable details. The report must be filed with the Financial Crimes Enforcement Network (FinCEN) by the specified submission date.  

View All BOIR Submission Deadlines

How Does It Impact Your Missouri Business?  

The CTA has far-reaching implications for a wide range of Missouri businesses. Understanding how it impacts your organization is crucial for ensuring compliance and avoiding potential legal and financial consequences. Here are a few key points:  

  • Who Must File: Most entities registered with the state are required to file a BOIR.  
  • Filing Deadlines: These vary based on when the business was officially established.   
  • Exemptions: There are exemptions, including 23 types of entities.  

For qualifying businesses, compliance is crucial. Failing to meet the CTA reporting requirements can result in legal and financial repercussions.   

Learn More About CTA Exemptions  

How Fraudsters Are Leveraging It  

With new regulations come new opportunities for fraudsters. There are reports of spammers exploiting the CTA by posing as regulatory bodies or legal entities to extract sensitive information from unknowing businesses. They might trick business owners using emails, phone calls, or fake websites. It’s vital to verify the legitimacy of any request for company information and be cautious of unsolicited communication related to the CTA.  


Contact The Business Banking Team

How Businesses Can Prevent Banking Fraud

A Business Guide to Scam & Fraud Prevention

Building a thriving business requires juggling multiple tasks and demands at once. Modern fraudsters attempt to target the busyness of day-to-day operations with deceptive account tactics that are easy to overlook, like fake invoices. Fortunately, by understanding how these thieves work, you can get ahead of their tactics and prevent business banking fraud.

Common Types of Business Fraud Tactics

From small sole proprietorships to large, corporate enterprises, companies typically have a consistent flow of accounts receivables and payables. These steady movements are a prime target for fraudsters looking to prey on businesses.

Invoice Fraud

A common risk is thieves posing as legitimate companies and sending invoices for goods or services that the business never received. In some cases, the bill may utilize a new company name in an industry that the recipient regularly utilizes, preventing it from standing out. Alternatively, the fraudsters may choose to identify as a well-known brand that elicits trust, such as Best Buy or PayPal.

When slipping under the radar isn’t effective, the fraudsters move on to scare tactics. For example, they may follow up a fake invoice with a late payment notice, threatening additional fees and even legal action if not paid immediately. Such a warning can cause significant fear, leading to businesses paying the fake amount and losing money.

Phishing Scams

Phishing has become a top choice for fraudsters, resulting in over $52 million in losses each year. With email phishing, the scammers send emails that appear to be from legitimate sources, such as your bank. They often use enticing tactics, like special offers, or fear-based requests, such as verifying an account change that wasn’t made.

When you click a link, it takes you to a fraudulent page that mimics the real website, requesting log-in details. These cybercriminals then use your credentials to transfer funds to an outside account. They can also send out invoices to your clients posing as your business. When unsuspecting customers pay, the fraudsters reroute the funds to themselves.Business Banking in Ashland, MO | Shot of pretty young business woman working with computer while consulting some invoices and documents in the kitchen at home.
5 Strategies to Prevent Business Banking Fraud

Fraudsters can access email and other contact details through a variety of methods, including harvesting software and third-party databases. Additionally, addresses for paper invoices are easily obtained through local business records. For these reasons, it’s challenging for businesses to avoid phishing attempts completely. However, you can stay a step ahead with a few strategic processes.

1. Track Vendors

Staying aware of the people and companies your business works with limits a cybercriminal’s options. As such, create a complete database of all the vendors you work with, along with contact information and an overview of what they provide to your team. Anytime a bill comes in that you don’t recognize, check to make sure the company is on the list.

2. Verify Invoices

When invoices do come in from familiar operations, always check that the bill is authentic. Avoid replying to the email or using the contact details provided. Instead, visit the company website or use the phone number you have on file to reach out to the brand and verify that the bill is real. Check with your team as well to make sure the services and products — and the accompanying amount — are correct and haven’t been paid already.

3. Monitor Finances Closely

Tracking movements of funds is an excellent way to spot discrepancies. Check all business banking accounts on a daily basis, and complete audits regularly to ensure that all transactions line up correctly. Additionally, set digital banking monitoring alerts to ensure unusual activity gets your attention immediately.

4. Train Staff

Our digital banking features allow businesses to add sub-users so that necessary individuals within your company can complete mandated tasks. While individual permissions can be set, it’s important to limit the number of users to reduce risk.

For those that do have access, make sure they’re properly trained on what to look out for, like transactions into or out of dormant accounts. All employees also need education on common email phishing tactics and their signs, such as spelling errors and odd formatting.

5. Stay Skeptical

In the digital age, fraudsters evolve their tactics incredibly quickly. As such, keeping your business secure requires always double-checking any incident that seems out of the ordinary. If unsure, reach out to your business banking team for a more in-depth review before approving any movement of money.

A Fraud Prevention Checklist for Business Banking Clients

☑ Enable Security Features
When logging on to digital banking for the first time, make sure to add your phone number and preferred contact method to receive your secure access code for multi-factor authentication.

☑ Keep Contact Information Up to Date
Let us get in touch quickly if we detect suspicious banking activity by regularly checking and updating your contact details.

☑ Set Up Alerts
Create custom alerts for each business account to catch unusual behavior as soon as it happens.

☑ Limit Digital Banking Access
Only select trustworthy individuals to have direct access, if necessary, and be sure to personalize their permissions based on the specific needs of their role.

☑ Create Internal Procedures
Prioritize fraud prevention training and education for the whole team, and put procedures in place to follow in the event suspicious activity does occur.

Rely on Secure Business Banking Services in Mid-Missouri

Successful fraud prevention begins with secure business banking services. At The Callaway Bank, we’re dedicated to keeping our clients protected across Columbia, Fulton, and surrounding areas throughout mid-Missouri. Our state-of-the-art fraud monitoring system automatically generates alerts for suspicious transactions. We also utilize a variety of enhanced security features for our digital banking services, including firewalls, multi-factor authentication, and encryption.

Enjoy the peace of mind of our secure banking services by reaching out to our Business Banking Team today!


Contact The Business Banking Team
How Local Banking Benefits the Community

Knowledge of the many benefits provided by shopping locally has become widespread. Yet, one piece of the sentiment that’s often overlooked is local banking. As with other types of businesses, choosing to work with independent institutions within the community can provide far-reaching rewards for both businesses and individuals alike. If you’re still relying on national chains, here’s a closer look at why it’s time to make the switch.

Why to Choose Local Banking

Keep Funds Local

When you invest money locally, those dollars don’t just evaporate to some corporate headquarters across the country or around the world. Instead, they stay in the community, where they’re reinvested between three and six more times. For instance, research shows when consumers spend $100 at a chain store, only $13 stays in the local community, on average. However, when depositing that same amount at a local business like The Callaway Bank, the number rises to a healthier $48.

Build a Stronger Local Economy

View of Fulton, MO, Main Street with Local Banking Logo These additional funds may go on to help grow small businesses, which increases job opportunities and brings even more money into the community. They can also attract desirable residents and assist with improvement projects, like sidewalk maintenance and park updates. As a result, keeping your hard-earned cash local can end up helping provide a higher quality of life for your family.
Keep Your Money Safe

Banking local also provides peace of mind. A community bank’s focus is entirely local, which often results in taking fewer financial risks and maintaining higher standards. In fact, while big banks across the U.S. were failing during the financial crisis, research shows that local banks were not only surviving but thriving. For that reason, you can bank with the knowledge that your funds are secured.

How to Bank Local With the For Your Community CD

Investing money locally has many clear benefits, and at The Callaway Bank, we don’t just do business in the community; we live in it. As an independent community bank, our neighborhoods are more than just our livelihood; all our decisions center around giving back. That’s why we do all we can to support our local community, including the push to get more individuals to shop local, ourselves as well.

For that reason, we created a unique banking offer for our customers across Callaway, Boone, and the surrounding counties. The “For Your Community CD” is an exceptional investment opportunity that provides a premium rate and supports your community by keeping your dollars local.  Reach out to find which option is right for you!

Contact Us

New Credit Card Login Portals

Upgraded Credit Card Management is coming!

November 8, 2021, the online credit card management webpages for business and personal credit cards are getting upgraded with improved navigation for your phone, tablet, or laptop, PLUS additional tools for your Callaway Bank business credit cards!


Beginning the evening of Thursday, November 4 through Monday, November 8 (mid-morning) the credit card login pages will not be accessible. We apologize in advance for any inconvenience this might cause. However, we’re excited for you to take the new website for a test drive Monday, November 8 as soon as they go live!


Two New Websites:

The new system has two options which are tailored to whether you have a personal or business card.

Option 1:  Business Cards
Managing your Business Credit Cards is easier than ever!

With Spendtrack®, the online portal for business credit cards, you can manage all your credit cards, for you and your team, from your phone, tablet, and computer, making it easy to stay up to date with the latest from your team. Plus, you will get these new features in one simple place:

  • Lock and unlock business credit cards if they are stolen or misplaced.
  • Easily communicate with your team using notifications to help ensure every team member receives changes you want to see for your spending activity at your company.
  • View your company and individual spend trends and activity based on merchant type.

Here is what the Spendtrack login screen will look like:

Spendtrack portal login


Option 2: Personal Cards
Credit Card Manager

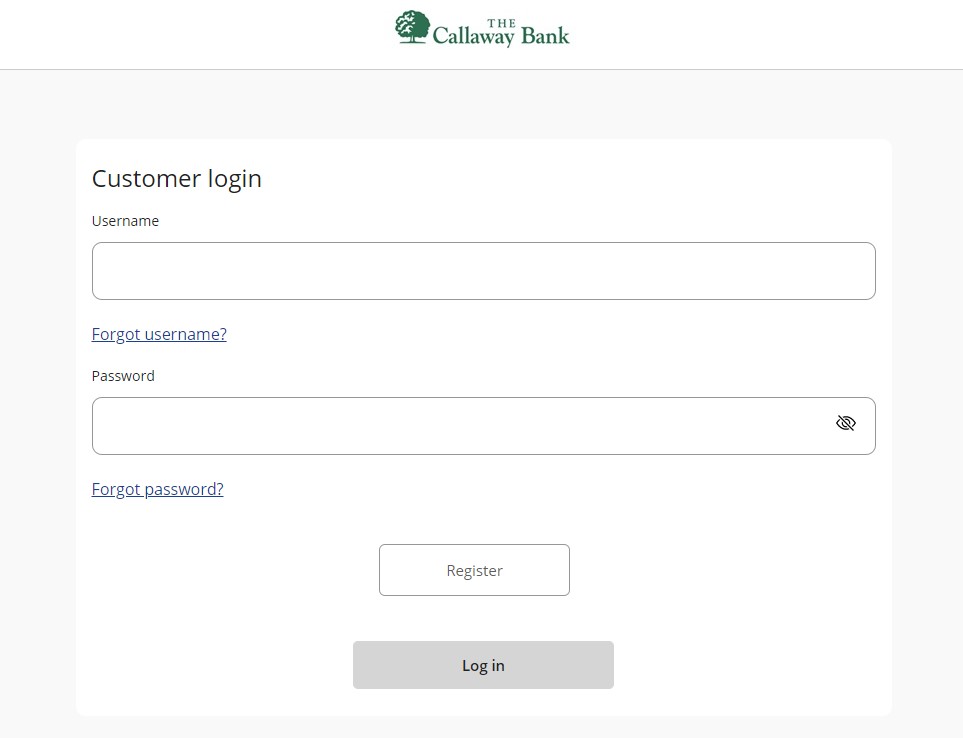
With the Credit Card Manager site, you will have an easier-to-navigate user interface you can use with your laptop, phone, or other mobile devices. The Credit Card Manager login screen can be seen here:

credit card portal login


For any questions regarding your account or the login process, please don’t hesitate to contact us using video chat, text, call, or email!

The Benefits of a Revolving Line of Credit for Your Business

Businesses sometimes require financial assistance and flexibility due to a variety of reasons or concerns. A revolving line of credit is a financing option offered to businesses to provide them with an influx of available capital for use — making it more similar to a credit card than a small business loan. But you might be wondering, how does a revolving line of credit work, and how does it differ from a business credit card?

Good question.

A business line of credit is the open availability to access capital for expenses and costs that arise. A line of credit allows businesses to receive cash to cover costs that couldn’t otherwise be purchased with a credit card.

It’s also important to note the differences between revolving and non-revolving lines of credit. A revolving credit, allows businesses to spend up to the credit limit. Even if you don’t use the credit, it won’t expire or close. Non-revolving credit is a lump-sum of capital that’s received all at once, and when the line is paid off, it closes.

Exploring a revolving line of credit opens a variety of doors for businesses of all sizes, and gives business owners the adaptability they need through all the ups and downs that accompany the market.

Here are the multiple benefits of obtaining a revolving line of credit for your business.

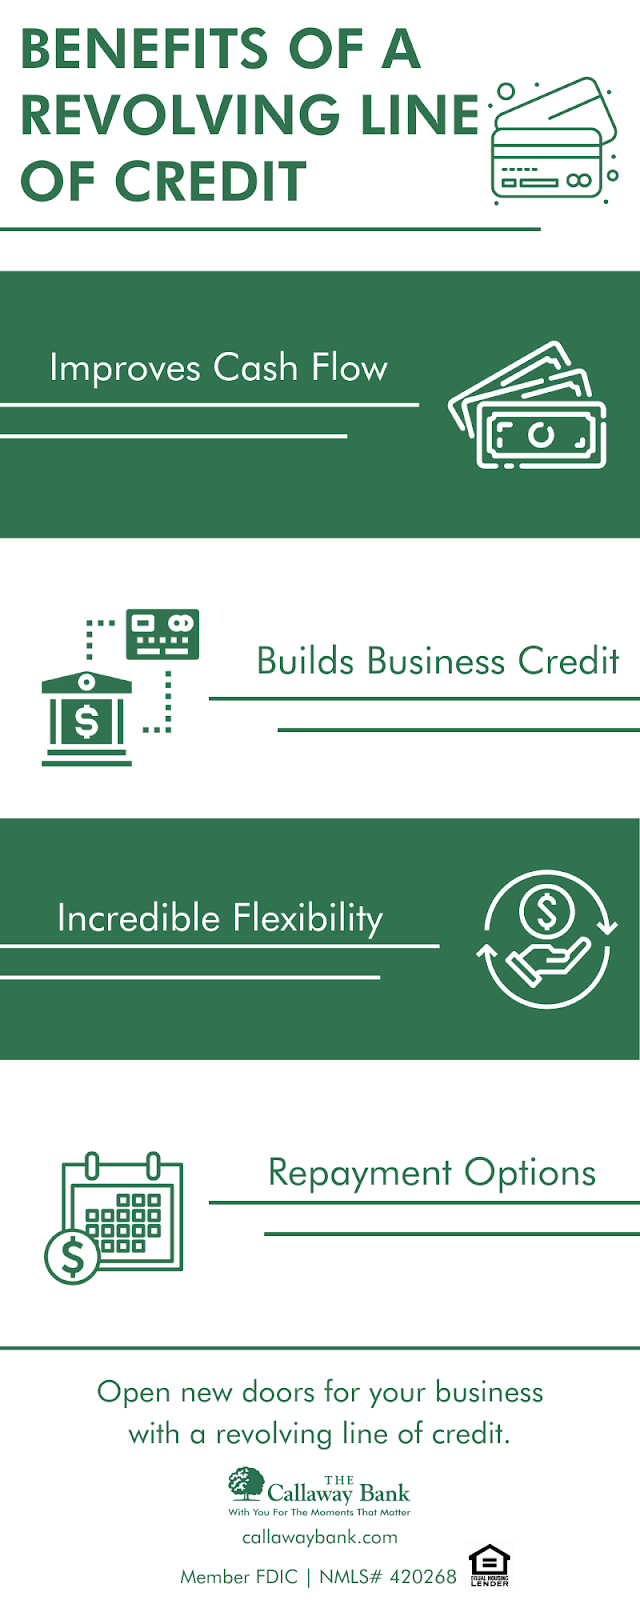
Improves Cash Flow

Managing cash flow is critical to the stability and success of a business. A line of credit helps businesses pay for inventory, payroll, and any other fixed or sudden expenses. A revolving line of credit is a popular option for businesses during their slow season to help offset a momentary loss in profits.

Builds Business Credit

Improving and maintaining a business credit score that is in good standing, is essential to a business’s financial future. Opening a revolving line of credit serves as a good way to further build credit. Just stay on top of payments and manage the growing interest.

Incredible Flexibility

Maybe the biggest reason to open a revolving line of credit is to provide your business with unmatched flexibility. Businesses can use the line to cover a variety of general operating expenses when cash flow is tight. An owner might need to buy inventory that will be sold soon, but payment from the customer might not come for another 45 days. The line of credit gives her the flexibility because she can draw funds from it to cover that cash flow crunch. Once payment is received, she pays down the line, and it’s ready to be used again. Only the next time she uses it to cover payroll or utilities. This unimpeded capital flexibility gives business owners the short-term ability to make decisions for any necessity or growth opportunity they encounter

Repayment Options

A revolving line of credit gives businesses repayment variability as to how and when the loan is repaid. For example, a seasonal business can postpone repayment on a revolving line of credit until cash flow supports it. This helps businesses better move money throughout the business, without being handcuffed to strict repayment terms and deadlines.

With You For the Moments That Matter

Regardless of the size of your business, The Callaway Bank is here to help guide and support you. Please view our Business Banking page for our full range of business services.